Explore potential car finance repayments with our Car Loan Repayment Calculator. Test different loan amounts, interest rates and repayment periods, and view detailed amortisation charts to see how repayments, interest costs and loan balances may change over time.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Car Loan Details:
Important!
Car Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Loan Amortisation Calculator
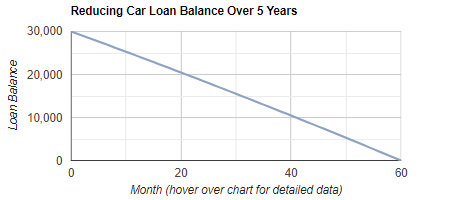
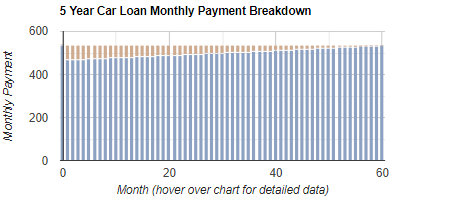
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Car Loan Repayment Calculator
Our Car Loan Repayment Calculator helps you estimate repayments for an Australian car loan and see how your balance, interest and principal change over time. It is important because small changes to the loan amount, term or interest rate can materially affect your monthly budget and the total interest you pay. The amortisation charts make it easier to compare scenarios and choose a structure you can afford with confidence.
General information only: This calculator provides an estimate and does not take into account your objectives, financial situation or needs. Results are indicative and your actual interest rate and repayments will depend on the lender, your credit profile and the final loan contract (including fees and conditions).
How to complete each section for the best result:
1. Purchase Price
Enter the vehicle purchase price as a whole number (no decimals or commas). If you plan to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts here so the estimate better reflects your likely loan size.
2. Deposit or Trade-in Value
Enter your cash deposit and/or trade-in value as a whole number. A higher deposit reduces the amount financed and usually lowers repayments and total interest.
3. Term of Loan (Years)
Select the number of years you want to repay the loan over. Shorter terms usually mean higher repayments but lower total interest. Longer terms can reduce monthly repayments but typically increase total interest paid.
4. Interest Rate (% per annum)
Select an interest rate to simulate. If you have a quote, choose the closest rate. If comparing options, run multiple calculations to see the impact of different rates.
5. Calculate
Click calculate to generate your results and charts.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability, leaving buffer for running costs and rate changes.
2. Amortisation charts: One chart shows the loan balance reducing over time; the other shows how early repayments are often interest-heavy and gradually shift toward principal repayment.
3. Comparison planning: Re-run the calculator with different terms, deposits and rates to identify a repayment level and total interest outcome that suits your budget.
Finance brokers can help Australian borrowers understand loan options, prepare an application and approach suitable lenders. This guide explains what brokers do, how the broker process works, what information borrowers may need to provide, and how fees and commissions can apply. - read more
Acquiring a loan as a self-employed individual in Australia can often feel like navigating a labyrinth. Without the regular pay cheques and conventional financial documentation typically provided by salaried employees, self-employed Australians face unique challenges in proving their creditworthiness to lenders. - read more
Personal loans have become an increasingly popular financial tool among millennials in Australia. As the cost of living rises and life goals such as buying a home or pursuing higher education loom on the horizon, personal loans offer a means to achieve these goals with more immediate access to funds. However, the array of options and terms can be bewildering, making it crucial for young adults to approach borrowing with a prudent mindset. - read more
Understanding the Debt-to-Income Ratio (DTI) is a crucial step toward solidifying your status as a creditworthy loan applicant. DTI is a key determinant used by lenders to gauge your ability to manage monthly payments and repay debts. It's essentially a numerical comparison between your total monthly debt and your gross monthly income, serving as a beacon of your financial health to potential creditors. - read more
Navigating the complexities of loan repayments can be daunting, but understanding the components and their impact on our financial health is essential. In Australia, a wise approach to loan repayment not only alleviates financial strain but directly influences our credit scores and future borrowing capacity. - read more
New November personal loan data is a reminder that Australian borrowers are not shopping in a single-rate market. Canstar’s latest update, published on 11 November 2026 using database figures from 6 November, shows some advertised rates remain below 6% per annum, while unsecured personal loan rates can extend to more than 29% depending on lender, product type and borrower profile. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more