Anyloan Australia JetSki Loan Repayment Calculator
Explore potential jet ski finance scenarios with our Jet Ski Loan Calculator. Test different loan amounts, interest rates and repayment terms, and view detailed amortisation charts to see how your estimated repayments, interest costs and loan balance may change over time.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
JetSki Loan Details:
Important!
Jetski Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Jetski Loan Amortisation Calculator
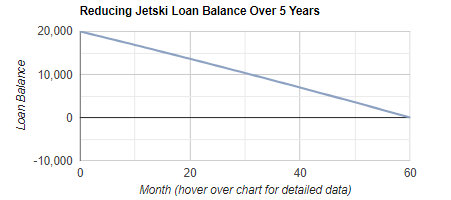
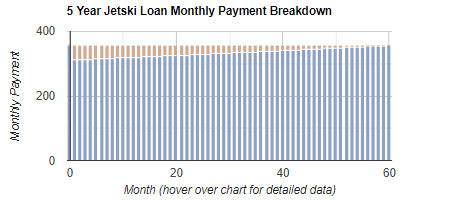
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our JetSki Loan Repayment Calculator
Our JetSki Loan Repayment Calculator helps you estimate your jet ski loan repayments before you apply for finance. It is designed to support better budgeting by showing how the loan amount, interest rate and term affect your estimated monthly repayment, total interest cost, and the way your balance reduces over time. This matters because a lower repayment can look attractive, but a longer term can materially increase the overall cost of your jet ski finance.
How to complete the form for the best result:
1. Purchase Price: Enter the jet ski purchase price as a whole number. For a more realistic estimate, consider whether you need to include on-road or setup costs where applicable, plus optional extras you may be financing (for example trailer, safety gear, insurance premiums if financed, or other fees charged by the lender). The calculator expects whole numbers only.
2. Deposit or Trade-in Value: Enter any cash deposit or the value of a trade-in as a whole number. A higher deposit generally reduces the loan amount, which can reduce your repayments and total interest.
3. Term of Loan: Select the number of years you want to repay the loan. Shorter terms usually mean higher repayments but lower total interest. Longer terms usually mean lower repayments but a higher total cost overall.
4. Interest Rate: Choose an interest rate to simulate your scenario. The rate options are indicative only. Your actual rate may differ based on factors such as credit history, employment, loan size and lender policies.
5. Calculate: Click calculate to generate your results.
How to interpret the results:
1. Repayment estimate: Use the repayment figure as a budgeting guide and stress-test it by increasing the interest rate or shortening the term.
2. Amortisation charts: Review the balance reduction chart to see how quickly you build equity, and the interest versus principal chart to understand how early repayments often include a higher interest component.
ASIC compliance note: This calculator provides general information and estimates only, and does not consider your objectives, financial situation or needs. Results may exclude fees, charges and any comparison rate impacts. Consider your contract terms and total cost before proceeding.
Getting your loan approved is a significant milestone, but it also opens the door to many new responsibilities. Proper management of your finances after loan approval is crucial to avoid common pitfalls that could derail your financial stability. - read more
As Australians navigate their personal financial journey, understanding how to manage debt effectively becomes crucial. From dealing with various lines of credit to juggling personal loans, the concept of debt consolidation often emerges as a viable strategy to regain control of financial health. This guide delves deep into the heart of debt consolidation's landscape in Australia, offering a comprehensive examination of what it entails, its benefits, and its potential drawbacks. - read more
Vehicle and equipment finance can help Australian individuals, sole traders and businesses access cars, utes, trucks, machinery and other assets without paying the full purchase price upfront. This guide explains common finance structures, key costs, risks and application factors to understand before applying. - read more
Financial wellbeing is often a balancing act that many Australians find challenging. In an age where the cost of living seems to climb incessantly, managing money effectively has never been more critical. Yet, despite the importance of financial literacy, many individuals struggle to break free from the cycle of poor budgeting and erratic spending habits. - read more
Loan agreements can be difficult to interpret, especially when interest rates, fees, repayment schedules and contract conditions are presented in technical language. This guide explains the key loan terms Australian borrowers commonly encounter so you can read loan documents more confidently and compare borrowing options with a clearer understanding of cost and flexibility. - read more
New November personal loan data is a reminder that Australian borrowers are not shopping in a single-rate market. Canstar’s latest update, published on 11 November 2026 using database figures from 6 November, shows some advertised rates remain below 6% per annum, while unsecured personal loan rates can extend to more than 29% depending on lender, product type and borrower profile. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more