Anyloan Australia Caravan Loan Repayment Calculator
Plan your next adventure with our Caravan Loan Repayment Calculator. Estimate repayments, view amortization charts, and compare finance options with ease.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Caravan Loan Details:
Important!
Caravan Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Caravan Loan Amortisation Calculator
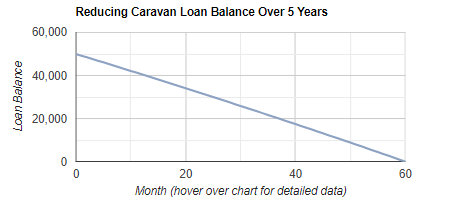
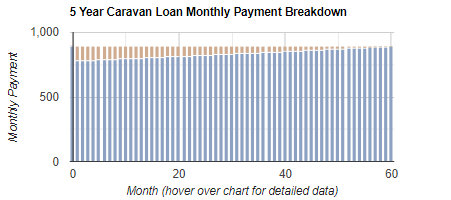
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Caravan Loan Repayment Calculator
Our Caravan Loan Repayment Calculator helps you estimate your likely monthly caravan loan repayments, understand how much interest you may pay over time, and visualise your loan via amortisation charts. It’s important because small changes to your purchase price, deposit, loan term or interest rate can materially affect cash flow and the total cost of caravan finance, helping you plan a realistic budget before you apply.
How to complete the form for the best result
1. Purchase Price
Enter the full caravan purchase price you expect to finance. If you plan to roll costs into the loan, consider adding likely upfront expenses such as registration, insurance and other on-road costs (where applicable). Use whole numbers only (no decimals or commas) to match the calculator format.
2. Deposit or Trade-in Value (if applicable)
Add any cash deposit and/or the trade-in value of an existing caravan. If you have no deposit or trade-in, leave this field blank. A higher deposit generally reduces the amount borrowed and can lower repayments and total interest.
3. Term of Loan (years)
Select the number of years you want to repay over. Longer terms usually reduce monthly repayments but increase the overall cost of the loan due to more interest over time. Choose a term that fits your budget with a buffer for rate rises and living costs.
4. Interest Rate (percent per annum)
Select an interest rate to simulate. The listed range is indicative only and your actual rate can only be confirmed after you apply, based on factors like credit history and employment.
5. Calculate
Click calculate to generate your estimated repayment and amortisation charts.
How to interpret the results
1. Repayment estimate
Use the monthly repayment figure as a budgeting guide, then compare scenarios by adjusting the term, deposit and interest rate.
2. Amortisation charts
The loan balance chart shows how your debt reduces month by month. The interest versus principal chart highlights that early repayments typically include a higher interest portion, with more of each payment going to principal later in the term.
Important information (ASIC-style general guidance)
Results are estimates and do not constitute a quote. They may not include fees, charges, or lender-specific features. This information is general and does not consider your objectives, financial situation or needs. Consider whether a caravan loan is appropriate for you and seek personalised advice if required. Credit is subject to approval and terms and conditions.
As we step into the year 2024, the financial landscape continues to evolve, bringing to the fore the ever-critical subject of interest rates. For anyone considering taking out a loan, whether for a car, a home, or personal expenses, understanding the mechanics of interest rates is not just beneficial; it’s essential. - read more
With the rising costs of living and the all-too-familiar financial hurdles, saving for large purchases can seem like a daunting task for many Australians. From buying a new car to securing the deposit on a home, significant expenses require a level of financial commitment and foresight that goes beyond everyday spending. - read more
For many self-employed Australians, securing a loan can feel like a daunting task. Unlike salaried employees, self-employed individuals often face unique challenges when it comes to proving their income stability and financial health. - read more
The loan approval process can often seem complex and daunting, but understanding what it entails is the first step toward boosting your chances. In essence, loan approval is the lender's process of assessing whether you are a viable candidate for the loan you have applied for. This involves evaluating your financial history, current financial status, and the potential risks involved in lending to you. - read more
Vehicle and equipment finance can help Australian individuals, sole traders and businesses access cars, utes, trucks, machinery and other assets without paying the full purchase price upfront. This guide explains common finance structures, key costs, risks and application factors to understand before applying. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more
The latest Reserve Bank lending-rate data gives Australian small business owners another reason to look beyond the first offer on the table. While business credit has continued to expand through 2026, the price paid by smaller borrowers remains highly dependent on loan structure, security, trading history and lender appetite. - read more
The Reserve Bank’s latest financial aggregates add another chapter to the borrowing story that has been building through 2026. The July update indicates that private sector credit is still expanding, with business lending remaining an important source of momentum. For SMEs, sole traders and self-employed borrowers, this extends the pattern seen in the earlier June credit data: demand for funding has not disappeared, even while interest rates and lender scrutiny continue to shape approval outcomes. - read more
The Reserve Bank’s latest meeting minutes have added more detail to the message borrowers heard after the earlier August rate decision: policy makers are not yet ready to declare victory over inflation, even if some parts of the economy are clearly slowing. For households, sole traders and SMEs, that means borrowing plans still need to be built around current lending conditions rather than expectations of a quick fall in rates. - read more
All finance quotes are provided free (via our secure server) and without
obligation. We respect your
privacy.
Knowledgebase
Credit Default Swap (CDS): A financial derivative or contract that allows an investor to "swap" or offset their credit risk with that of another investor.