Anyloan Australia Plant & Equipment Lease Calculator
Explore potential equipment leasing scenarios with our Plant & Equipment Lease Calculator. Test different lease amounts, residual (balloon) payments and repayment terms to estimate costs and see how varying finance assumptions may influence your business repayments and cash flow.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Business Asset Lease Details:
Important!
Business Asset Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Asset Lease Amortisation Calculator
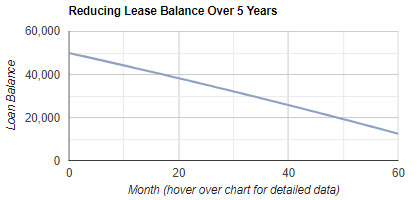
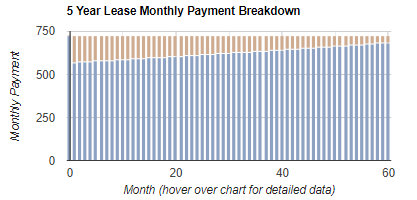
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Plant & Equipment Lease Calculator
Our Plant & Equipment Lease Calculator helps business owners estimate lease repayments before you speak with a lender. It’s important because changing the residual (balloon), term and interest rate can materially affect cash flow, total interest paid and the end-of-term payout amount. The calculator provides estimates only and is general information, not personal advice; consider your objectives, financial situation and needs, and check the lease contract, fees and tax treatment with your accountant or adviser.
How to complete the calculator (best-practice order):
1. Purchase Price: Enter the total amount you want to finance, using whole numbers only (no dots or commas). Include relevant on-road and acquisition costs you intend to finance, such as applicable tax, stamp duty, registration, insurance or other costs.
2. Balloon or Residual Value: Choose the residual as a percentage of the purchase price. A higher residual usually lowers the ongoing repayments, but increases the amount due at the end and can increase the overall cost across the term. Select a residual that matches your expected end-of-term plan (refinance, trade-in, or pay out).
3. Term of Loan: Select the number of years. Longer terms typically reduce repayments but can increase total interest paid. Use a term that aligns with the asset’s useful life and how long you expect to keep it.
4. Interest Rate: Select a rate to simulate. The displayed range is indicative only; your actual rate depends on the lender and your circumstances and can only be confirmed after you apply.
5. Calculate: Run the estimate, then re-run scenarios to compare different residuals, terms and rates for a clearer view of affordability versus total cost.
How to interpret the results:
1. Repayment estimate: Treat this as a guide for budgeting, not a quote.
2. Residual due: Note the end-of-term balloon amount you’ll need to pay or refinance.
3. Amortisation graphs: Review how the balance reduces over time and how each repayment splits between interest and principal, which helps you understand cost versus payoff progress.
Debt management involves strategies and practices designed to help individuals control their debt and maintain a healthy financial standing. It includes everything from budgeting and tracking expenses to negotiating better terms with creditors and consolidating debts for easier repayment. - read more
Understanding the Debt-to-Income Ratio (DTI) is a crucial step toward solidifying your status as a creditworthy loan applicant. DTI is a key determinant used by lenders to gauge your ability to manage monthly payments and repay debts. It's essentially a numerical comparison between your total monthly debt and your gross monthly income, serving as a beacon of your financial health to potential creditors. - read more
In today's digital age, the landscape of borrowing has evolved with the emergence of online loans. The convenience and accessibility offered by online lenders have made them an increasingly popular choice for Australians seeking financial assistance. However, it is essential to approach online borrowing with caution and make informed decisions to ensure smart borrowing practices. - read more
Business loan security, collateral and personal guarantees can affect how lenders assess risk, what documents they request and what may happen if repayments are not met. This guide explains the key concepts for Australian small business borrowers. - read more
For new borrowers, stepping into the world of loans can be overwhelming. There are numerous options available, and each comes with its own set of terms, interest rates, and features. - read more
New November personal loan data is a reminder that Australian borrowers are not shopping in a single-rate market. Canstar’s latest update, published on 11 November 2026 using database figures from 6 November, shows some advertised rates remain below 6% per annum, while unsecured personal loan rates can extend to more than 29% depending on lender, product type and borrower profile. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more