Calculate home loan repayments with our Home Loan Repayment Calculator. View detailed amortization charts, compare loan terms, and plan your mortgage with confidence.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Home Loan Details:
Important!
Home Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote, please CLICK HERE
Home Loan Amortisation Calculator
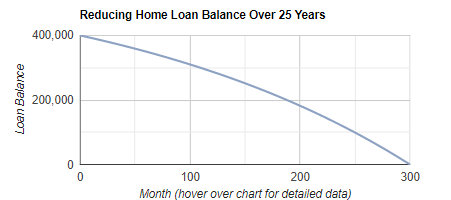
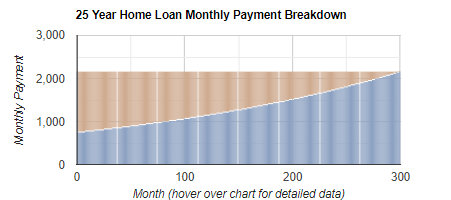
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Home Loan Repayment Calculator
Our Home Loan Repayment Calculator helps you estimate your mortgage repayments in Australia and understand how a loan may reduce over time. It is useful for budgeting, comparing loan terms, and visualising an amortisation schedule (how each repayment is split between interest and principal). The calculator is designed for planning only and works best when you enter realistic assumptions.
Important information: Results are estimates only and do not constitute a quote. Interest rates and loan features vary by lender and may change. This information is general and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you and seek professional advice if required.
How to complete the calculator fields (in order):
1. Purchase Price: Enter the property purchase price. If you expect to borrow extra for costs, you may choose to include amounts such as stamp duty, insurance, and other buying costs in this figure so your estimate reflects your likely loan size. Enter whole numbers only (no dots or commas).
2. Deposit or Equity Value: Enter your cash deposit or usable equity from another property (if applicable). A higher deposit generally reduces the loan amount and can lower repayments. Enter whole numbers only (no dots or commas).
3. Term of Loan (years): Select the number of years to repay the loan. Longer terms usually reduce repayments but increase total interest paid over the life of the loan.
4. Interest Rate (% per annum): Select an interest rate for the simulation. Use a realistic rate and consider testing higher rates to understand “rate rise” risk.
5. Calculate: Click calculate to generate your results.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability checks, remembering real loans may include fees and different features.
2. Amortisation charts: Review the loan balance chart to see how your balance falls over time, and the interest versus principal chart to understand how early repayments are typically interest-heavy, then shift toward principal reduction later.
3. Compare scenarios: Adjust the term, deposit/equity, or interest rate and recalculate to compare loan terms and see how changes affect repayments and total interest over time.
As Australians navigate their personal financial journey, understanding how to manage debt effectively becomes crucial. From dealing with various lines of credit to juggling personal loans, the concept of debt consolidation often emerges as a viable strategy to regain control of financial health. This guide delves deep into the heart of debt consolidation's landscape in Australia, offering a comprehensive examination of what it entails, its benefits, and its potential drawbacks. - read more
Financial health is a crucial aspect of overall well-being, particularly in the ever-evolving economic landscape of Australia. The capacity to manage personal finances effectively not only provides a sense of security but also opens doors to opportunities that might otherwise be out of reach. As such, mastering the art of money management is an indispensable skill for Australians from all walks of life. - read more
A solid financial plan helps you understand where your money is going, set practical goals and prepare for major life decisions such as buying a home, purchasing a car, investing, protecting your family or planning for retirement. This guide explains the main building blocks of financial planning in an Australian context, without replacing personalised financial advice. - read more
In today's digital age, the landscape of borrowing has evolved with the emergence of online loans. The convenience and accessibility offered by online lenders have made them an increasingly popular choice for Australians seeking financial assistance. However, it is essential to approach online borrowing with caution and make informed decisions to ensure smart borrowing practices. - read more
Understanding the loan application process can be quite challenging. However, with the right tools, it becomes much easier to navigate. One of these essential tools is a loan calculator. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more
The latest Reserve Bank lending-rate data gives Australian small business owners another reason to look beyond the first offer on the table. While business credit has continued to expand through 2026, the price paid by smaller borrowers remains highly dependent on loan structure, security, trading history and lender appetite. - read more
The Reserve Bank’s latest financial aggregates add another chapter to the borrowing story that has been building through 2026. The July update indicates that private sector credit is still expanding, with business lending remaining an important source of momentum. For SMEs, sole traders and self-employed borrowers, this extends the pattern seen in the earlier June credit data: demand for funding has not disappeared, even while interest rates and lender scrutiny continue to shape approval outcomes. - read more
The Reserve Bank’s latest meeting minutes have added more detail to the message borrowers heard after the earlier August rate decision: policy makers are not yet ready to declare victory over inflation, even if some parts of the economy are clearly slowing. For households, sole traders and SMEs, that means borrowing plans still need to be built around current lending conditions rather than expectations of a quick fall in rates. - read more
The Reserve Bank of Australia’s August decision to leave the cash rate unchanged at 4.35% keeps a familiar message in place for Australian borrowers: relief may come eventually, but loan decisions still need to be made on today’s numbers. For households, sole traders and SMEs, the practical issue is not only where rates sit now, but how lenders assess affordability while policy remains restrictive. - read more
Find out now if you qualify and
compare rates, offers and options from multiple lenders - without a credit check!
All finance quotes are provided free (via our secure server) and without
obligation. We respect your
privacy.
Knowledgebase
Equity Release: A way for homeowners to release cash from the value of their home, either as a lump sum or in installments, while still living in the property.