Anyloan Australia Business Loan Repayment Calculator
Explore potential business finance scenarios with our Business Loan Calculator. Test different borrowing amounts, interest rate assumptions and loan structures to see how various scenarios may influence your estimated repayments and overall finance costs.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Loan Amortisation Calculator
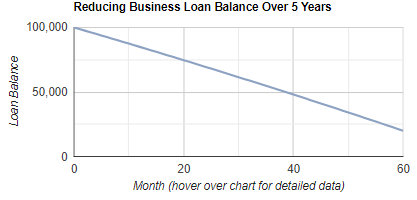
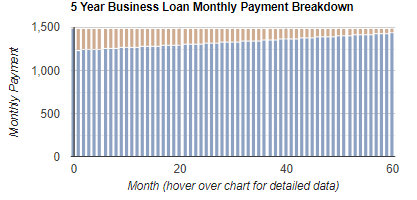
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
Understanding your borrowing power is an essential step for anyone looking to take out a loan. This concept represents the amount of money you're eligible to borrow from a lender, whether it’s for purchasing a home, a car, or investing in your future. Knowing your borrowing power not only sets realistic expectations but also guides you in financial planning and budgeting for your loan repayments. - read more
Starting a business is an exciting venture, often filled with dreams and aspirations of growing a successful enterprise. For many first-time entrepreneurs, securing a business loan can be a crucial step in turning these dreams into reality. Business loans provide the necessary funds for growth and expansion, enabling startups to invest in equipment, hire employees, and expand marketing efforts. - read more
With the rising costs of living and the all-too-familiar financial hurdles, saving for large purchases can seem like a daunting task for many Australians. From buying a new car to securing the deposit on a home, significant expenses require a level of financial commitment and foresight that goes beyond everyday spending. - read more
Debt consolidation loans serve a crucial purpose in the financial toolbelt of individuals juggling multiple debts. At its core, consolidation is the process of combining several loans or liabilities into one single loan. This technique is not just a clerical convenience but a strategic move that can transform repayment chaos into manageable order. By merging debts, borrowers can often secure better interest rates, lower monthly payments, and a more transparent repayment timeline. - read more
Loan management skills are crucial for individuals and families in Australia, as they play a vital role in managing finances and achieving financial stability. Effective loan management enables individuals to make sound financial decisions and avoid falling into debt traps. This article aims to highlight the importance of acquiring loan management skills and how it can benefit Australians. - read more
New November personal loan data is a reminder that Australian borrowers are not shopping in a single-rate market. Canstar’s latest update, published on 11 November 2026 using database figures from 6 November, shows some advertised rates remain below 6% per annum, while unsecured personal loan rates can extend to more than 29% depending on lender, product type and borrower profile. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more
Debt Consolidation: Debt consolidation usually involves negotiating a new loan to pay other existing loans in order to get more favourable interest rates and terms.