The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
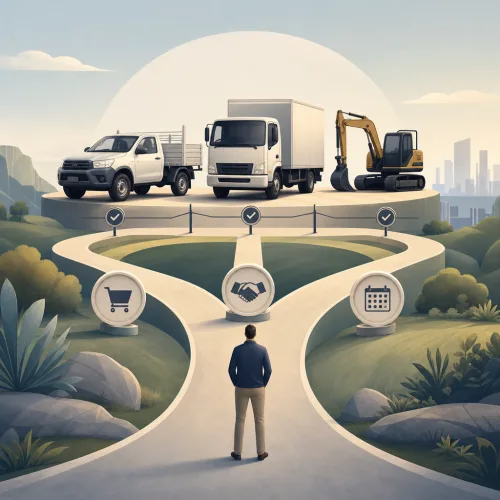
Vehicle and equipment finance can help Australian individuals, sole traders and businesses access cars, utes, trucks, machinery and other assets without paying the full purchase price upfront. This guide explains common finance structures, key costs, risks and application factors to understand before applying.
Vehicle finance and equipment finance are commonly used in Australia to fund cars, utes, trucks, trailers, machinery, tools, fit-outs and other income-producing assets. Instead of paying the full cost upfront, a borrower or business usually repays the finance over an agreed term, often with the asset itself used as security.
These products can be useful, but the structure matters. A chattel mortgage, hire purchase arrangement, finance lease or operating lease can affect cash flow, ownership, tax treatment, flexibility and end-of-term choices. This article provides general educational information about how vehicle finance Australia and equipment finance Australia typically work. It does not consider your personal objectives, financial situation or needs.
What is vehicle and equipment finance?
Vehicle and equipment finance is a broad term for lending or leasing arrangements used to acquire a specific asset. The asset may be for personal use, business use or a combination of both, depending on the product and lender criteria.
Common financed assets include:
- cars, utes, vans and motorcycles;
- trucks, trailers and commercial vehicles;
- excavators, forklifts and construction machinery;
- agricultural equipment;
- medical, dental or professional equipment;
- hospitality, manufacturing or office equipment;
- technology, tools and fit-out items, where accepted by the lender.
In many asset finance arrangements, the lender takes a security interest over the asset. This means the asset may help support the loan application, but it also means the lender may have rights over the asset if repayments are not met. The exact rights and obligations depend on the contract, the purpose of the finance and the applicable law.
If you are comparing personal and business finance categories more broadly, the Anyloan Australia homepage outlines the types of loan and leasing options commonly considered by Australian borrowers.
Common types of vehicle and equipment finance in Australia
Different finance structures can look similar at first because they may all involve regular repayments for an asset. The important differences are usually ownership, end-of-term options, tax and accounting treatment, flexibility and responsibility for running costs.
Chattel mortgage
A chattel mortgage is commonly used by businesses and sole traders to buy vehicles or equipment. Under this structure, the borrower generally owns the asset from the start, while the lender registers a security interest over it until the loan is repaid.
Chattel mortgages are often used for business vehicles, trucks and equipment because they can provide clear ownership while spreading the cost over time. Some arrangements include a balloon payment, which is a larger final payment due at the end of the term. A balloon may reduce regular repayments, but it does not remove the debt. The borrower still needs a plan to pay, refinance or otherwise deal with that final amount.
Hire purchase
Hire purchase generally involves hiring the asset over the finance term, with ownership transferring after all required payments and any final amount are made. It can suit borrowers who want eventual ownership but prefer a structured repayment arrangement.
The terms can vary between providers, so it is important to understand when ownership transfers, what happens if you want to exit early, and whether there are fees, residual amounts or other conditions.
Finance lease
A finance lease allows a business to use an asset for an agreed period while making lease payments. The financier usually owns the asset during the lease term. At the end, there may be options such as paying a residual value, refinancing, returning the asset or upgrading, depending on the contract.
Finance leases can be useful where a business wants to use an asset without purchasing it outright at the start. However, the residual value and end-of-term obligations need careful attention.
Operating lease or equipment rental
An operating lease or rental arrangement is generally more focused on access and use than ownership. The provider may retain ownership, and the borrower or business pays to use the asset for a set period. Some arrangements may include maintenance or replacement options, although this depends on the provider and product.
This structure can suit equipment that becomes outdated quickly or assets a business does not want to own long term. The trade-off is that you may not build ownership in the asset, and contract restrictions may apply.
Consumer car loans and personal vehicle finance
Individuals may use secured or unsecured personal loans to buy a car or other vehicle. With a secured car loan, the vehicle is commonly used as security. With an unsecured personal loan, the lender does not take the same type of asset security, but the interest rate, fees, borrowing limit and approval criteria may differ.
Consumer vehicle loans are generally assessed against the borrower's personal income, expenses, liabilities and credit history. Approval, pricing and loan terms depend on lender criteria and the applicant's circumstances.
Lease vs buy equipment: practical differences
The choice between leasing and buying business equipment is not just about the monthly repayment. It can affect ownership, cash flow, tax treatment, flexibility and what happens when the asset needs replacement.
| Factor |
Buying with finance |
Leasing or rental |
| Ownership |
You may own the asset from the start or after final payment, depending on the structure. |
The financier or provider commonly owns the asset during the term. |
| Cash flow |
Repayments spread the purchase cost, but deposits, fees or balloon payments may apply. |
Payments may be structured for use of the asset, often with end-of-term conditions. |
| Flexibility |
You may have more control over the asset, subject to lender security and contract terms. |
May provide upgrade or return options, but restrictions can apply. |
| End of term |
You may own the asset outright once all obligations are met. |
You may need to return, buy, refinance or renew, depending on the agreement. |
| Asset obsolescence |
You carry the risk that the asset loses value or becomes outdated. |
Some arrangements may help manage upgrade cycles, depending on the provider. |
There is no single structure that suits every borrower. A tradie buying a ute, a cafe leasing coffee equipment, a transport business financing a truck and an individual purchasing a family car may all need different arrangements.
Interest rates, fees, balloons and residual values
When comparing vehicle finance Australia or equipment finance Australia, the headline repayment is only one part of the cost. Borrowers should consider the total amount payable over the term and the conditions attached to the finance.
Key cost components may include:
- Interest rate: the rate charged on the amount financed. It may be fixed or variable, depending on the product.
- Fees and charges: these may include establishment fees, monthly fees, documentation fees, early payout costs or other charges.
- Deposit or upfront contribution: some borrowers contribute cash or trade-in value to reduce the financed amount.
- Balloon payment: a larger final payment on some loan structures, often used to reduce regular repayments.
- Residual value: an estimated end-of-term value used in some lease structures. The borrower may have obligations connected to this amount.
- Term length: a longer term may reduce regular repayments but can increase total interest paid. A shorter term may increase repayment pressure.
Before applying, it can be helpful to model different repayment scenarios using available loan calculators. Calculator results are estimates only and should be checked against actual lender quotes and contract terms.
How lenders assess asset finance applications
Lenders assess asset finance applications differently depending on whether the borrower is an individual, sole trader, company, trust or partnership. They also consider the asset type, age, condition, intended use and resale value.
Common assessment factors include:
- Income and cash flow: lenders want to understand whether repayments appear manageable.
- Credit history: personal and, where relevant, business credit history may be reviewed.
- Existing debts and commitments: current loans, credit cards, leases and business liabilities can affect serviceability.
- Asset quality: newer, readily saleable assets may be viewed differently from specialised or older equipment.
- Business trading history: for business equipment leasing or loans, lenders may consider how long the business has traded and how stable its revenue appears.
- Documentation: bank statements, financial statements, BAS, tax returns, invoices, quotes and identification may be requested, depending on the application.
- Loan purpose: lenders may want to understand whether the asset is for personal use, business use or mixed use.
Some lenders offer low-doc or alternative-documentation options for certain business borrowers, but availability, pricing and approval criteria vary. Providing incomplete or inaccurate information can delay an application or affect the outcome.
Business, tax and accounting considerations
Business asset finance can have tax and accounting implications. For example, ownership, GST treatment, depreciation, interest deductibility and lease payment treatment may differ depending on the structure and how the asset is used.
These issues are specific to the borrower, the asset and the business structure. A registered tax agent or accountant can help explain how a chattel mortgage, hire purchase agreement, lease or rental arrangement may be treated for your circumstances. Borrowers should not choose a finance product based only on a general tax assumption.
Risks to understand before applying
Asset finance can support growth or help manage cash flow, but it also creates ongoing obligations. Important risks include:
- Repayment pressure: if income falls, the repayment may still be due.
- Asset repossession: if the asset secures the finance and repayments are not met, the lender may have rights to recover it.
- Balloon or residual exposure: a large end-of-term amount can create cash flow pressure if not planned for.
- Early exit costs: paying out or ending a contract early may involve fees or other costs.
- Asset value risk: the asset may depreciate faster than expected or become obsolete.
- Insurance and maintenance obligations: borrowers may need to keep the asset insured, registered and maintained.
- Business-use assumptions: if an asset is expected to generate income but does not perform as planned, repayments can become harder to manage.
Reading the contract carefully is essential. If you are unsure about terms such as default interest, security, guarantees, payout figures or residual values, seek clarification before signing.
Questions to ask before choosing vehicle or equipment finance
Before applying for vehicle finance or equipment finance, consider asking:
- Do I want to own the asset, or only use it for a set period?
- How long will the asset remain useful for my needs?
- What is the total amount payable over the full term?
- Are there upfront fees, ongoing fees or early payout costs?
- Is there a balloon payment or residual value, and how will I manage it?
- What happens if I want to sell, upgrade or replace the asset early?
- What insurance, servicing or maintenance obligations apply?
- Will the repayments remain manageable if income changes?
- For business use, have I checked the tax and accounting treatment with a qualified adviser?
- Have I compared more than one lender or structure?
How a broker may assist with asset finance
Asset finance can involve product differences that are not always obvious from a repayment quote. A finance broker may help identify suitable lender options to compare, explain documentation requirements and assist with submitting an application. Brokers do not control lender approval, pricing or conditions, and outcomes depend on lender criteria and the applicant's circumstances.
If you would like to understand how broker support may fit into the process, you can read more about Anyloan's broker support options.
Final thoughts
Vehicle and equipment finance can be a practical way to access important assets while spreading the cost over time. The right structure depends on the asset, how it will be used, your cash flow, your preference for ownership, and the terms offered by lenders or lease providers.
Before applying, compare the total cost, understand the contract, plan for any balloon or residual amount, and consider professional tax or accounting advice where business use is involved. A well-prepared application and a clear understanding of the finance structure can help you make a more informed borrowing decision.
Published: Friday, 31st Jul 2026
Author: Paige Estritori



I’ve been caught by a balloon payment before, so modelling equipment finance over the full term is definitely worth doing before signing.