
APRA Ends International Bank of Australia's Restricted Licence
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
The Australian Prudential Regulation Authority (APRA) has complied with a request by International Bank of Australia Pty Limited to terminate its restricted licence as an authorised deposit-taking institution (ADI).
Similarly, IBOA Group Holdings Pty Ltd (IBOA Holdings) has rescinded its status as a non-operating holding company (NOHC).
This information is according to a recent update from APRA's official channels.
Previously, in November 2022, APRA granted the licences under the Banking Act 1959, providing International Bank of Australia the restricted ADI status and offering IBOA Holdings NOHC credentials. Despite these opportunities, the bank never moved forward with launching any products, nor did it establish customer relationships or attract any deposits during this period.
The specific reasons behind International Bank of Australia’s decision to relinquish its restricted ADI licence remain speculative. However, industry experts suggest it could be a strategic shift in focus or re-evaluation of the Australian market landscape. It is important to note that this decision does not close the door for any future applications the bank might make to re-enter the ADI or restricted ADI landscape.
This instance highlights a rare, yet noteworthy, event where a financial institution pulls back after initial regulatory approval but before market penetration. It provides a contrast to other emerging banks that take swift action post-approval to acquire market share and customer base.
For those keeping an eye on regulatory activities and ADI listings, APRA maintains updated records of all such authorised entities. The registers of authorised deposit-taking institutions and non-operating holding companies can be accessed openly on the APRA website. Financial services observers will find these registers an essential tool for staying updated on the operational status of various financial institutions.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more
The latest Reserve Bank lending-rate data gives Australian small business owners another reason to look beyond the first offer on the table. While business credit has continued to expand through 2026, the price paid by smaller borrowers remains highly dependent on loan structure, security, trading history and lender appetite. - read more
The Reserve Bank’s latest financial aggregates add another chapter to the borrowing story that has been building through 2026. The July update indicates that private sector credit is still expanding, with business lending remaining an important source of momentum. For SMEs, sole traders and self-employed borrowers, this extends the pattern seen in the earlier June credit data: demand for funding has not disappeared, even while interest rates and lender scrutiny continue to shape approval outcomes. - read more
Getting your loan approved is a significant milestone, but it also opens the door to many new responsibilities. Proper management of your finances after loan approval is crucial to avoid common pitfalls that could derail your financial stability. - read more
Welcome to the beginning of your financial journey. As an Australian, understanding the nuances of financial planning is pivotal to securing your economic future. Whether you're applying for your first loan or on the cusp of retirement, the financial decisions you make will have a lasting impact on your life. This guide aims to walk you through each stage, providing practical advice that you can apply to your own circumstances. - read more
Acquiring a loan as a self-employed individual in Australia can often feel like navigating a labyrinth. Without the regular pay cheques and conventional financial documentation typically provided by salaried employees, self-employed Australians face unique challenges in proving their creditworthiness to lenders. - read more
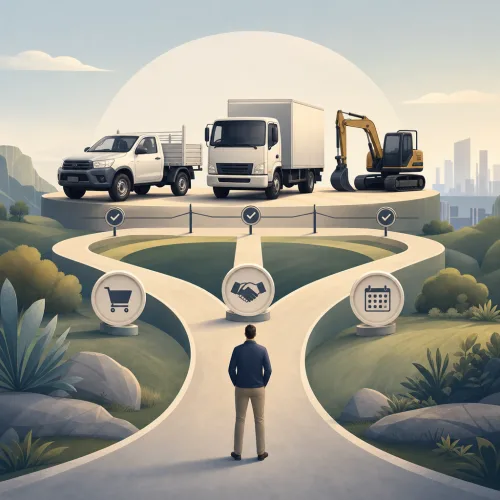
Vehicle and equipment finance can help Australian individuals, sole traders and businesses access cars, utes, trucks, machinery and other assets without paying the full purchase price upfront. This guide explains common finance structures, key costs, risks and application factors to understand before applying. - read more
For new borrowers, stepping into the world of loans can be overwhelming. There are numerous options available, and each comes with its own set of terms, interest rates, and features. - read more
Knowledgebase
Interest-Only Loan: A type of loan where the borrower only pays the interest on the principal balance for a set term.
No comments yet. Be the first to share your thoughts.