

Anyloan Australia :: Articles

Good Debt Versus Bad Debt

What is the difference between good debt and bad debt?

Good Debt Versus Bad Debt

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

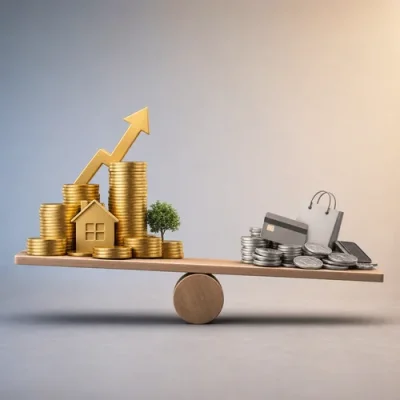
Some people see debt as a curse. Others see it as a friend. Debt can make you miserable, or it can be used to make you wealthy beyond your wildest dreams. The trouble is, how do we know what is good and what is bad?

Well it basically boils down to this. Good debt puts money in your pocket after you have paid for the debt (interest), and bad debt takes money from your pocket on an ongoing basis.

In todays society, the world has gone through an explosion in bad debt. In the United States for example, for every $1 a person earns, they spend $1.20.

In Australia things are getting worse too. We spend $1.02 for every dollar earned. Back in the 1980's we would earn $1 and save 20c.

Bad Debt

The single most influencing factor in this curse of bad debt is the credit card. It is so easy to get a credit card these days, and even school kids have them. Most people I know have several of them, and you know what, they max them all out. People get caught in this vicious circle of paying one card off with another, and still the interest bill compounds at an alarming rate.

It is not only credit cards that are doing the damage, it is also the ability to get three years interest free furniture and home appliances with no money down. This is a huge trap, and when people live beyond their means and do not have the means to pay back their debt in the given time they are hit with massive interest rates and so the cycle continues.

So that is bad debt, and I didn't even include cars, holidays and clothes, all charged up on your card! You get the picture.

Good Debt

Now onto good debt. Personally, I love good debt, and any wealthy person will tell you the same thing. With good debt you can purchase income producing assets that put cash in your pocket, even after the interest bill is paid.

AnyLoan Australia Weekly NewsCast

Podcast Cover Image This week: lenders continue repricing after the RBAs November move to 4.85%, with updates still landing by Friday. The RBAs 9 November speech highlights ongoing inflation pressures from AI‑related investment, oil prices and capacity constraints, so plan for rates to stay higher for longer. The Aussie dollar sits around 68 US cents as of Friday, affecting imported equipment and vehicle costs for SMEs considering leasing versus buying. RBA minutes arrive Tuesday, 17 November. Visit anyloan.com.au for guides, comparisons and calculators.

Some examples of this include property, shares and stocks, and your own business. It even includes things such as art, wine and other rare collectibles.

By leveraging other peoples money to buy such things, you are after a time able to put yourself into a fantastic financial position, and you can now begin to pay cash for those bad debt items like expensive clothes and exotic holidays.

When I was at school there was never any lessons on good and bad debt, and I'm pretty sure they still do not teach effective money and debt management.

It is unfortunate that in a society such as ours, that the government does not teach this to every man, woman and child as it has a massive impact on our lives. Just look at the sub prime fallout in the States to see how people who overextended themselves are now really in trouble.

There is a way out if you are in bad debt, and there are resources out there to financially educate yourself before you do get into any trouble.

We only have ourselves to rely upon to shape our financial future, and the longer we leave it the harder it gets. Eradicate the bad debt from your lives, and begin to live without that heavy weight around your neck.

Published: Wednesday, 25th Aug 2021
Author: 95

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Finance Articles

The Impact of Credit Scores on Loan Applications: How to Borrow Smartly
Credit scores play a crucial role in loan applications, determining eligibility and interest rates for borrowers. Understanding how credit scores are calculated and the impact they have on loan applications is essential for anyone who wants to borrow smartly. - read more
Understanding Loan Calculators: A Practical Guide for Smart Borrowers
Understanding the loan application process can be quite challenging. However, with the right tools, it becomes much easier to navigate. One of these essential tools is a loan calculator. - read more
Avoiding Loan Rejection: How to Present Yourself as a Creditworthy Applicant
Understanding the Debt-to-Income Ratio (DTI) is a crucial step toward solidifying your status as a creditworthy loan applicant. DTI is a key determinant used by lenders to gauge your ability to manage monthly payments and repay debts. It's essentially a numerical comparison between your total monthly debt and your gross monthly income, serving as a beacon of your financial health to potential creditors. - read more
Top Mistakes to Avoid After Getting Your Loan Approved
Getting your loan approved is a significant milestone, but it also opens the door to many new responsibilities. Proper management of your finances after loan approval is crucial to avoid common pitfalls that could derail your financial stability. - read more
Common Business Loan Options for Australian Small Businesses
Australian small businesses can access several types of finance, including secured loans, unsecured loans, lines of credit, overdrafts, invoice finance, asset finance and working capital loans. This guide explains how common options differ and what to compare before applying. - read more

Finance News

Personal loan rates still demand more than a quick glance
11 Nov 2026: Paige Estritori
New November personal loan data is a reminder that Australian borrowers are not shopping in a single-rate market. Canstar’s latest update, published on 11 November 2026 using database figures from 6 November, shows some advertised rates remain below 6% per annum, while unsecured personal loan rates can extend to more than 29% depending on lender, product type and borrower profile. - read more
Latest RBA Increase Resets the Numbers for Borrowers
04 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC Review Highlights the Need to Question Costlier Loan Recommendations
28 Oct 2026: Paige Estritori
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
Borrowers Remain Resilient, but the RBA Is Watching the Edges
24 Oct 2026: Paige Estritori
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Why loan purpose can still change the rate you pay
16 Sep 2026: Paige Estritori
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more

Knowledgebase
Equity Release:
A way for homeowners to release cash from the value of their home, either as a lump sum or in installments, while still living in the property.


Quick Links: | Personal And Business Loans Australia | Business Loan Options | Personal Loans Australia | Leasing Finance Solutions | Finance Brokers Australia | Unsecured Business Loans | Vehicle And Equipment Finance | Compare Finance Quotes | Quick Loan Approval | Low Interest Loans | Flexible Loan Terms