Anyloan Australia :: Articles

Why did my Credit Score drop - and how can I fix it?

What causes my credit score to drop and how can I improve it?

Why did my Credit Score drop - and how can I fix it?

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

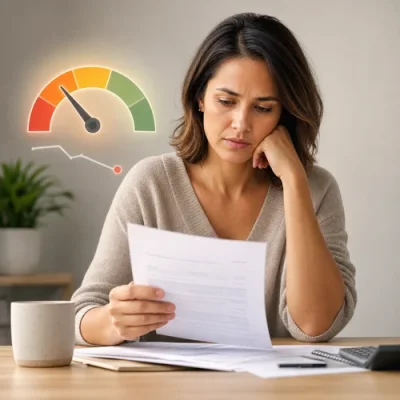
Your Credit Rating (or Credit Score) plays a very important role in determining your eligibility to get a loan. Here we look at the reasons why your credit score may drop and some handy tips to avoid this problem.

Your credit rating is very important. It is used to determine how much interest you need to pay. It is also a reflection of your creditworthiness.

If you have high credit rating, you can enjoy lower interest charges on loans. Apart from that, you also get higher credit limit and great deals on your credit card.

If you find that your rating has dropped significantly, this may mean that you may have made a financial mistake.

There are a number of reasons why you may suddenly have a lower score.

If you know what these reasons are, there is a chance that you can avoid or at least fix your current dilemma. Here are some possible causes of abrupt score drop and how you may be able to avoid them.

Late Payments

Your payments reflect 35% of your FICO score, regardless of whether you pay on time or not.

If you missed a payment, this will not completely damage your rating. However, if you turn this into a habit, your score will eventually be affected.

Moreover, your creditor may charge you with more fees and you may likely end up having to make many more payments, which could include your credit card bills, immediate fees for missed payments, and charges on credit lines and later, loans.

The only solution to avoid all these is to pay your bills on time.

New Credit Card Application

Applying for a new card when you are struggling with paying another can hurt your credit score. Know that 10% of your credit rating is made up of new inquiries for credit.

New card applications will show on your credit report for 12 months.

If you wish to get a new card, do so with control. If you are to make an inquiry, do it only once as much as possible.

Income Insurance Online

Income Insurance Online logo Compare income insurance for self-employed & employed with a participating broker. Free broker quotes & no-cost referral service.

One inquiry is acceptable since your score can rebound within a year.

Credit Card Cancellation

You have the option to close your account if you have credit card debt.

However, doing so will actually damage your score, especially if your account carries a balance.

Another possible scenario is that creditors may cancel your account.

Both scenarios can have an effect on your rating; therefore, avoid credit card cancellation as much as possible.

Unemployment Benefits

If you are unemployed and you get benefits, this will have a slight effect on your score. It is advised that you receive the benefits for a short period only. Although the credit bureaus will not find out if you are unemployed, they will certainly see that your income has decreased.

High Credit to Debt Ratio

Your extended credit will take 30% of your credit score.

Sudden increase in balances without higher credit limit will result to a score drop.

If you have balances, strive to pay them off as soon as possible.

Poor Debt Management

Credit score is not only about what you do with your credit cards. There are other factors that can influence your score.

These include your lines of credit and loan balances, which comprise 30% of your FICO score.

If you have too much debt, your rating will definitely go down. It will also be difficult for you to afford the payments each month.

Hence, you should be able to manage your debt by lowering the amount of money you owe from various financial institutions.

Published: Wednesday, 18th Aug 2021
Author: 260

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Finance Articles

Understanding the Power of Pre-Approval in Your Financial Journey
Pre-approval in the financial world refers to a preliminary evaluation by a lender to determine how much credit or loan they may be willing to extend to an applicant. It's a vital step for any Australian looking to finance a significant purchase such as a home or a car. Essentially, pre-approval provides potential borrowers with an indication of their borrowing capacity, subject to final verification and approval. - read more
Top 10 Smart Borrowing Strategies for Australians: A Comprehensive Guide
Smart borrowing is crucial for individuals and businesses in Australia to manage their financial goals effectively. With a well thought-out borrowing strategy, you can optimize your finances, minimize costs, and achieve your financial objectives. - read more
Step-by-Step Guide to Navigating the Loan Application Process
Welcome to our step-by-step guide to navigating the loan application process! Whether you're seeking a home loan, personal loan, or business loan, the journey can seem overwhelming. - read more
Practical Financial Advice for Every Australian: From First Loans to Retirement
Welcome to the beginning of your financial journey. As an Australian, understanding the nuances of financial planning is pivotal to securing your economic future. Whether you're applying for your first loan or on the cusp of retirement, the financial decisions you make will have a lasting impact on your life. This guide aims to walk you through each stage, providing practical advice that you can apply to your own circumstances. - read more
How Much Can You Borrow? A Complete Guide to Assessing Your Borrowing Power
Understanding your borrowing power is an essential step for anyone looking to take out a loan. This concept represents the amount of money you're eligible to borrow from a lender, whether it’s for purchasing a home, a car, or investing in your future. Knowing your borrowing power not only sets realistic expectations but also guides you in financial planning and budgeting for your loan repayments. - read more

Finance News

Latest RBA Increase Resets the Numbers for Borrowers
04 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85% gives Australian borrowers a fresh reason to revisit their repayment assumptions. The move, effective from 4 November, follows updated RBA forecasts showing inflation staying higher for longer, with the central bank pointing to fuel costs, broader price pressures and tighter domestic capacity as reasons for further restraint. - read more
ASIC Review Highlights the Need to Question Costlier Loan Recommendations
28 Oct 2026: Paige Estritori
ASIC’s 13 October 2026 review of major mortgage broker groups has delivered a timely reminder for borrowers: a loan recommendation should be understandable, evidence-based and clearly connected to the customer’s needs. The regulator found that broker practices generally aligned with its guidance, but also identified gaps in how some higher-cost loan recommendations, supervision processes and complaints were handled. - read more
Borrowers Remain Resilient, but the RBA Is Watching the Edges
24 Oct 2026: Paige Estritori
The Reserve Bank of Australia’s October 2026 Financial Stability Review gives borrowers a mixed but useful message: the financial system remains broadly resilient, yet cost pressures, hardship requests and sector-specific business stress are still important warning signs for households and SMEs planning their next finance decision. - read more
Why loan purpose can still change the rate you pay
16 Sep 2026: Paige Estritori
Recent personal and vehicle loan rate updates are reinforcing a practical message for Australian borrowers: the reason you borrow, the asset involved and the strength of your application can still make a meaningful difference to the price you are offered. - read more
Why SME Borrowers Still Need to Shop Carefully for Finance
09 Sep 2026: Paige Estritori
The latest Reserve Bank lending-rate data gives Australian small business owners another reason to look beyond the first offer on the table. While business credit has continued to expand through 2026, the price paid by smaller borrowers remains highly dependent on loan structure, security, trading history and lender appetite. - read more

Knowledgebase
Personal Loan:
A Personal Loan is a means of obtaining finance from a financial institution or financial product provider and the lending criteria usually depends on criteria such as personal income and expenses, assets and liabilities, employment status and previo


Quick Links: | Personal And Business Loans Australia | Business Loan Options | Personal Loans Australia | Leasing Finance Solutions | Finance Brokers Australia | Unsecured Business Loans | Vehicle And Equipment Finance | Compare Finance Quotes | Quick Loan Approval | Low Interest Loans | Flexible Loan Terms